What Is the Difference Between Medicare Advantage and Medigap?

Trever Dahms • 22 May 2026

One of the most common questions I hear: "What's the difference between Medicare Advantage and a Medicare Supplement?"

If you're turning 65 or just reviewing your Medicare options, you've probably heard two terms thrown around: Medicare Advantage and Medigap (also called Medicare Supplement). They both work alongside Medicare, but they work very differently — and choosing the wrong one can cost you thousands of dollars a year.

This guide breaks down both options in plain language, with context specific to residents of Clearwater, Pinellas County, and the greater Tampa Bay area.

What Is Original Medicare?

Before comparing the two options, it helps to understand Original Medicare:

Part A covers hospital stays, skilled nursing, and some home health care.

Part B covers doctor visits, outpatient care, and preventive services.

Original Medicare pays about 80% of covered costs. The remaining 20% — plus deductibles and copays — is where the gap comes in. Both Medicare Advantage and Medigap are designed to address that gap, just in very different ways.

What Is Medicare Advantage (Part C)?

Medicare Advantage is an alternative to Original Medicare offered by private insurance companies approved by Medicare. Instead of using your red, white, and blue Medicare card, you use your Advantage plan card.

Most Medicare Advantage plans include:

— Medical coverage (Parts A and B)

— Prescription drug coverage (Part D)

— Often, extra benefits like dental, vision, hearing, and fitness

Many Advantage plans have $0 monthly premiums, though you still pay your Part B premium.

The catch: Advantage plans use provider networks (HMO or PPO), meaning your doctors and hospitals need to be in-network. Out-of-pocket costs like copays can add up if you're a frequent user of medical services.

What Is Medigap (Medicare Supplement)?

Medigap is a supplemental policy that works alongside Original Medicare — not instead of it. It picks up much of what Medicare doesn't pay: deductibles, coinsurance, and sometimes even foreign travel emergency coverage.

The biggest advantages of Medigap:

— Predictable costs — you know what you'll owe each month

— No networks — see any doctor who accepts Medicare, anywhere in the U.S.

— No referrals needed

The tradeoff: Medigap plans have a higher monthly premium, and most plans don't include drug coverage (you'd add a separate Part D plan).

Which Is Better for Residents of Clearwater and Pinellas County?

There's no universal answer — the right choice depends on your health, your doctors, your prescriptions, and your financial situation.

Medicare Advantage may make sense if:

— You're relatively healthy and don't use a lot of specialist care

— You want extra benefits like dental and vision included

— You prefer a lower monthly premium

— Your preferred doctors are in the plan's network

Medigap may make sense if:

— You have ongoing health conditions or expect high medical utilization

— You travel frequently or split time between states (snowbirds, take note)

— You want predictable, low out-of-pocket costs

— You don't want to worry about network restrictions

How TD Coverage Can Help

As an independent broker contracted with 70+ carriers in the Clearwater and Tampa Bay area, Trever Dahms can shop both Medicare Advantage and Medigap plans side-by-side — with no pressure and no bias toward any single carrier.

There's no cost to you for this service. Call Trever today at (262) 352-3997 or visit tdcoverage.com to get started.
by Trever Dahms • 28 September 2026
The Question Every Family Asks Eventually When a parent or spouse is diagnosed with dementia or Alzheimer's, one of the first questions families ask is what Medicare will cover. It's an important question, and unfortunately the answer is often not what families hope to hear. Original Medicare does not cover round-the-clock supervision or custodial care. That includes help with bathing, dressing, eating, or keeping someone safe if they wander. This is true even when the underlying diagnosis is dementia or Alzheimer's. What Medicare Will Cover Medicare can help with skilled home health care, but only under specific conditions: The patient must be considered homebound A doctor must certify the need for care and create a plan of care The care must involve skilled services, such as nursing visits, physical therapy, or speech therapy A home health aide can be included, but only as part of a skilled care plan, and hours are limited Medicare can also cover a limited stay in a skilled nursing facility after a qualifying hospital stay, but this is meant for short-term rehabilitation, not long-term custodial care. Where Medicaid Fits In Medicaid can cover long-term custodial care, including nursing home care and in some states in-home care, but only after a person has spent down most of their assets to meet the program's financial limits. For a lot of families, this means selling a home, spending savings, and going through a process that feels invasive at a time that's already emotionally difficult. It's not a bad option, it's just a last resort option, and it works best when families understand it ahead of time rather than in the middle of a crisis. Why I Bring Up Long Term Care Insurance Early This is exactly why I talk to clients about Long Term Care Insurance before they need it, especially if there's a family history of dementia or Alzheimer's. LTC insurance, or hybrid life and LTC policies, are really the only tools that let people plan ahead for this kind of care instead of reacting to it during a crisis. If you have a parent recently diagnosed, or you're thinking ahead for yourself, let's talk through what coverage actually looks like for your situation. Understanding your options now gives you and your family a lot more control later.
by Trever Dahms • 23 September 2026
Term life insurance tends to get pitched as a young person's product — something you buy in your 30s to protect a growing family, and then quietly let expire once the kids are grown. That's a fair use case, but it's not the whole story. For some people, term life still has a role to play well into their 50s, 60s, and beyond. 
by Trever Dahms • 16 September 2026
LTC Policies Aren't One Size Fits All. Long Term Care Insurance is one of those products where two policies can look similar on the surface and be completely different once you dig into the details. If you're comparing quotes, here are the features I always walk clients through.
by Trever Dahms • 31 August 2026
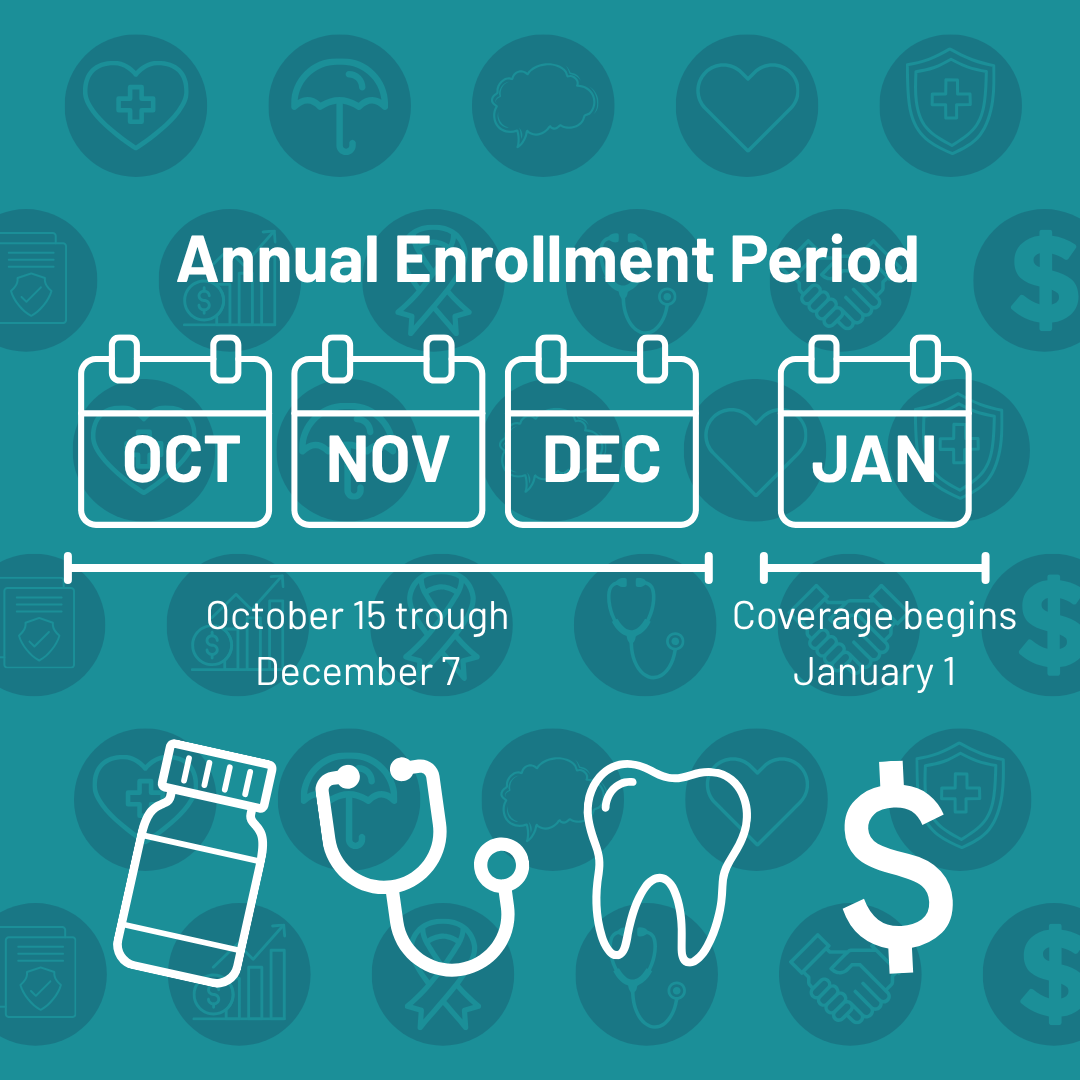
I think about all the people out there running the exact same Medicare Advantage plan they picked six or seven years ago, never once checking if it's still any good, kind of like people who still use the ringtone their phone came with because changing it never occurred to them. It was fine once. That doesn't mean it's still fine now. The Annual Enrollment Period (October 15 through December 7) is your one shot a year to actually do something about it. Here are five signs worth paying attention to.
by Trever Dahms • 25 August 2026
Okay so every October the same thing happens. Your mailbox turns into a warzone of postcards, all claiming to be the best plan, none of them actually explaining the rules of the game you're supposedly playing. It's like getting twelve different group texts about a party and nobody mentions the address. You're just standing there thinking, "Do I need to actually DO something here, or is this just insurance companies being insurance companies?
by Trever Dahms • 14 August 2026
Medicare Covers a Lot. It Doesn't Cover Everything.
by Trever Dahms • 10 August 2026
A Small Policy That Solves a Big Problem
by Trever Dahms • 3 August 2026
Two Different Tools for Two Different Goals Clients often come to me asking about annuities without knowing there are different types built for different purposes. Two of the most common are Multi-Year Guaranteed Annuities, or MYGAs, and Fixed Index Annuities, or FIAs. They're both about protecting principal, but they work differently.
by Trever Dahms • 29 July 2026
The Question I Wish More People Asked Earlier Most people don't think about long term care planning until they're already in the middle of a crisis, whether that's a parent's diagnosis or their own health scare. By that point, some of the best options are already off the table. So when should you actually start thinking about this?
by Trever Dahms • 22 July 2026
Missed Medicare's Annual Enrollment Period? A Special Enrollment Period may still let you change plans. Here's what qualifies and how it works.