Long Term Care — The Cost Nobody Talks About

Trever Dahms • 22 May 2026

Did you know the average cost of a private room in a Florida nursing home is over $100,000 per year?

One of the most common and costly misconceptions in retirement planning is the belief that Medicare will cover long-term care. The reality is very different — and the financial consequences of being unprepared can be devastating.

This guide explains what long-term care actually costs in Florida, what Medicare does and doesn't cover, and the planning options available to residents of Clearwater and the Tampa Bay area.

What Is Long-Term Care?

Long-term care refers to a range of services that help people with chronic illnesses, disabilities, or aging-related conditions manage daily activities over an extended period. This includes:

— Assistance with activities of daily living (ADLs): bathing, dressing, eating, toileting, transferring

— Memory care for those with Alzheimer's or dementia

— Assisted living facilities

— Skilled nursing facilities

— Home health aides

— Adult day care programs

What Does Long-Term Care Cost in Florida?

Costs vary by setting and level of care, but here are general benchmarks for Florida:

— Home Health Aide: $25–$35/hour (40+ hours/week adds up fast)

— Assisted Living Facility: $3,500–$5,500/month

— Memory Care Unit: $5,000–$8,000/month

— Skilled Nursing Facility (semi-private): $8,000–$10,000/month

— Skilled Nursing Facility (private room): $9,500–$12,000+/month

For context: two years in a private nursing facility could easily exceed $250,000.

What Does Medicare Cover for Long-Term Care?

Medicare provides very limited long-term care coverage:

— Skilled nursing facility stays: covered only after a qualifying 3-day hospital stay, and only for up to 100 days per benefit period — with significant copays after day 20

— Home health care: covered only if you're homebound and need skilled nursing or therapy

— Custodial care (help with ADLs, non-medical assistance): NOT covered by Medicare

Medicaid does cover long-term care — but only after you've spent down most of your assets to qualify. This is not a plan most people want to rely on.

Long-Term Care Insurance Options

There are several ways to plan for long-term care costs:

1. Traditional LTC Insurance: Standalone policy with a daily or monthly benefit. Premiums are lower when purchased younger and healthier.

2. Hybrid / Linked-Benefit Policies: Combine life insurance (or an annuity) with LTC benefits. If you never need care, the death benefit passes to your heirs. No "use it or lose it" concern.

3. Short-Term Care Insurance: More affordable, covers up to 12 months — a stepping stone for those who can't qualify for traditional LTC.

4. Life Insurance with LTC Rider: Add a long-term care acceleration rider to an existing or new life insurance policy.

When Should You Start Planning?

The best time to apply for long-term care coverage is in your 50s or early 60s — when you're likely still healthy enough to qualify and premiums are significantly lower.

Waiting until your health changes may limit your options or price you out of the market entirely.

Talk to a Local Expert

Trever Dahms at TD Coverage works with multiple carriers on long-term care solutions in Clearwater, FL, and the surrounding Tampa Bay area. He can walk you through traditional and hybrid options, compare costs, and help you find a solution that fits your budget and goals.

Call: (262) 352-3997

Visit: tdcoverage.com

by Trever Dahms • 28 September 2026
The Question Every Family Asks Eventually When a parent or spouse is diagnosed with dementia or Alzheimer's, one of the first questions families ask is what Medicare will cover. It's an important question, and unfortunately the answer is often not what families hope to hear. Original Medicare does not cover round-the-clock supervision or custodial care. That includes help with bathing, dressing, eating, or keeping someone safe if they wander. This is true even when the underlying diagnosis is dementia or Alzheimer's. What Medicare Will Cover Medicare can help with skilled home health care, but only under specific conditions: The patient must be considered homebound A doctor must certify the need for care and create a plan of care The care must involve skilled services, such as nursing visits, physical therapy, or speech therapy A home health aide can be included, but only as part of a skilled care plan, and hours are limited Medicare can also cover a limited stay in a skilled nursing facility after a qualifying hospital stay, but this is meant for short-term rehabilitation, not long-term custodial care. Where Medicaid Fits In Medicaid can cover long-term custodial care, including nursing home care and in some states in-home care, but only after a person has spent down most of their assets to meet the program's financial limits. For a lot of families, this means selling a home, spending savings, and going through a process that feels invasive at a time that's already emotionally difficult. It's not a bad option, it's just a last resort option, and it works best when families understand it ahead of time rather than in the middle of a crisis. Why I Bring Up Long Term Care Insurance Early This is exactly why I talk to clients about Long Term Care Insurance before they need it, especially if there's a family history of dementia or Alzheimer's. LTC insurance, or hybrid life and LTC policies, are really the only tools that let people plan ahead for this kind of care instead of reacting to it during a crisis. If you have a parent recently diagnosed, or you're thinking ahead for yourself, let's talk through what coverage actually looks like for your situation. Understanding your options now gives you and your family a lot more control later.
by Trever Dahms • 23 September 2026
Term life insurance tends to get pitched as a young person's product — something you buy in your 30s to protect a growing family, and then quietly let expire once the kids are grown. That's a fair use case, but it's not the whole story. For some people, term life still has a role to play well into their 50s, 60s, and beyond. 
by Trever Dahms • 16 September 2026
LTC Policies Aren't One Size Fits All. Long Term Care Insurance is one of those products where two policies can look similar on the surface and be completely different once you dig into the details. If you're comparing quotes, here are the features I always walk clients through.
by Trever Dahms • 31 August 2026
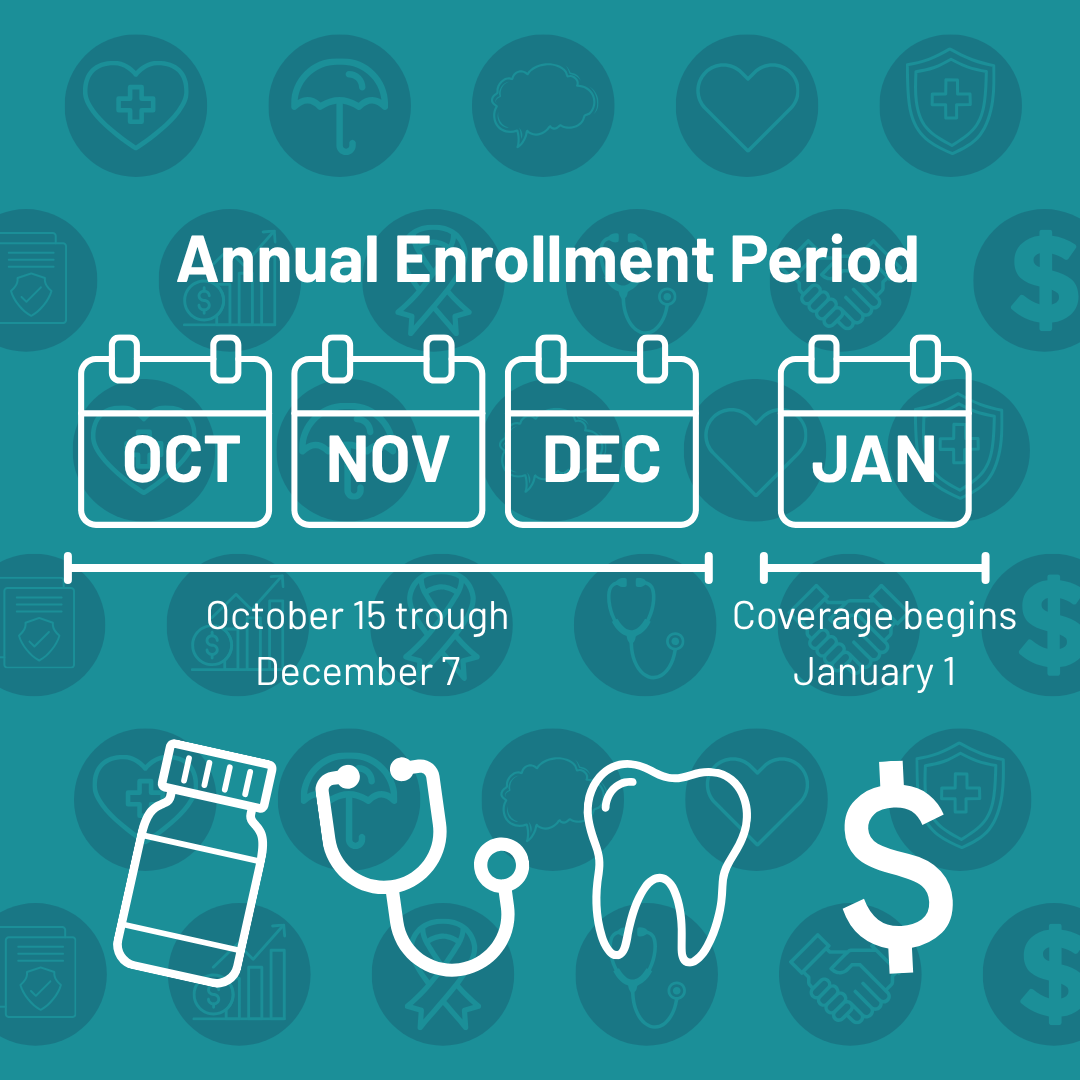
I think about all the people out there running the exact same Medicare Advantage plan they picked six or seven years ago, never once checking if it's still any good, kind of like people who still use the ringtone their phone came with because changing it never occurred to them. It was fine once. That doesn't mean it's still fine now. The Annual Enrollment Period (October 15 through December 7) is your one shot a year to actually do something about it. Here are five signs worth paying attention to.
by Trever Dahms • 25 August 2026
Okay so every October the same thing happens. Your mailbox turns into a warzone of postcards, all claiming to be the best plan, none of them actually explaining the rules of the game you're supposedly playing. It's like getting twelve different group texts about a party and nobody mentions the address. You're just standing there thinking, "Do I need to actually DO something here, or is this just insurance companies being insurance companies?
by Trever Dahms • 14 August 2026
Medicare Covers a Lot. It Doesn't Cover Everything.
by Trever Dahms • 10 August 2026
A Small Policy That Solves a Big Problem
by Trever Dahms • 3 August 2026
Two Different Tools for Two Different Goals Clients often come to me asking about annuities without knowing there are different types built for different purposes. Two of the most common are Multi-Year Guaranteed Annuities, or MYGAs, and Fixed Index Annuities, or FIAs. They're both about protecting principal, but they work differently.
by Trever Dahms • 29 July 2026
The Question I Wish More People Asked Earlier Most people don't think about long term care planning until they're already in the middle of a crisis, whether that's a parent's diagnosis or their own health scare. By that point, some of the best options are already off the table. So when should you actually start thinking about this?
by Trever Dahms • 22 July 2026
Missed Medicare's Annual Enrollment Period? A Special Enrollment Period may still let you change plans. Here's what qualifies and how it works.