Final Expense Insurance: What It Covers and Who Needs It
Trever Dahms • 10 August 2026
A Small Policy That Solves a Big Problem
Final Expense Insurance doesn't get talked about as much as term or whole life, but it solves a very real problem for a lot of families: making sure funeral and end-of-life costs don't fall on loved ones during an already difficult time.
What Final Expense Insurance Covers
This is a small whole life policy, typically ranging from a few thousand dollars up to around $25,000 to $50,000, designed to cover:
• Funeral and burial or cremation costs
• Outstanding medical bills
• Small debts left behind
• Any remaining household expenses during the transition period
Why It's Different From a Standard Life Policy
Final expense policies are built for simplicity. Coverage amounts are smaller, and underwriting is usually easier, often with simplified or guaranteed acceptance options. That makes it accessible for people who might not qualify for a larger term or whole life policy due to age or health conditions.
Who This Tends to Fit
• Seniors who don't have life insurance already in place
• Anyone who wants to make sure funeral costs don't become a burden on their family
• People who may not qualify for larger policies due to health history
• Those who want a simple, affordable way to leave something behind for final expenses
Peace of Mind, Not Just a Policy
I've had more than one client tell me this is the policy that let them stop worrying about being a burden on their kids. That's really what final expense insurance is about. It's not a huge policy, but it solves a real problem in a simple, affordable way.
If you want to see what coverage would look like for you, I can walk you through options from multiple carriers and find something that fits your budget.
Term life insurance tends to get pitched as a young person's product — something you buy in your 30s to protect a growing family, and then quietly let expire once the kids are grown. That's a fair use case, but it's not the whole story. For some people, term life still has a role to play well into their 50s, 60s, and beyond.
LTC Policies Aren't One Size Fits All. Long Term Care Insurance is one of those products where two policies can look similar on the surface and be completely different once you dig into the details. If you're comparing quotes, here are the features I always walk clients through.
I think about all the people out there running the exact same Medicare Advantage plan they picked six or seven years ago, never once checking if it's still any good, kind of like people who still use the ringtone their phone came with because changing it never occurred to them. It was fine once. That doesn't mean it's still fine now. The Annual Enrollment Period (October 15 through December 7) is your one shot a year to actually do something about it. Here are five signs worth paying attention to.
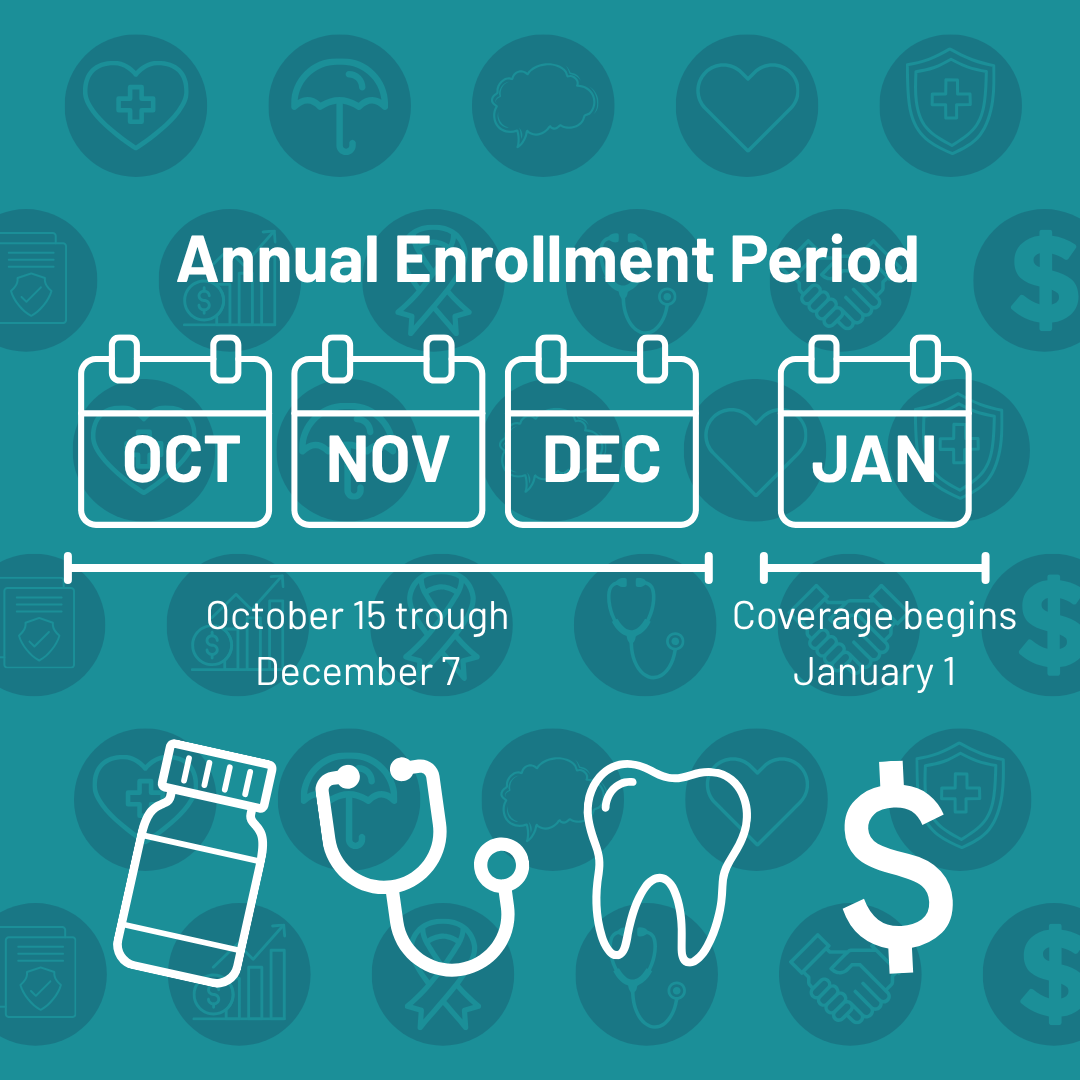
Okay so every October the same thing happens. Your mailbox turns into a warzone of postcards, all claiming to be the best plan, none of them actually explaining the rules of the game you're supposedly playing. It's like getting twelve different group texts about a party and nobody mentions the address. You're just standing there thinking, "Do I need to actually DO something here, or is this just insurance companies being insurance companies?
Medicare Covers a Lot. It Doesn't Cover Everything.
Two Different Tools for Two Different Goals Clients often come to me asking about annuities without knowing there are different types built for different purposes. Two of the most common are Multi-Year Guaranteed Annuities, or MYGAs, and Fixed Index Annuities, or FIAs. They're both about protecting principal, but they work differently.
The Question I Wish More People Asked Earlier Most people don't think about long term care planning until they're already in the middle of a crisis, whether that's a parent's diagnosis or their own health scare. By that point, some of the best options are already off the table. So when should you actually start thinking about this?
Missed Medicare's Annual Enrollment Period? A Special Enrollment Period may still let you change plans. Here's what qualifies and how it works.
Medicare is one of the most important financial decisions you’ll make in retirement. It’s also one of the easiest to get wrong — not because people aren’t paying attention, but because the rules are genuinely complicated and the consequences of certain mistakes are permanent.
For retirees and pre-retirees, few things are more unsettling than watching the stock market drop 20, 30, or even 40 percent. When you’re drawing income from your savings, a major market decline early in retirement can permanently damage your financial plan — a phenomenon called sequence-of-returns risk. Fixed Index Annuities (FIAs) are designed specifically to address this risk.